 3 hours ago
11

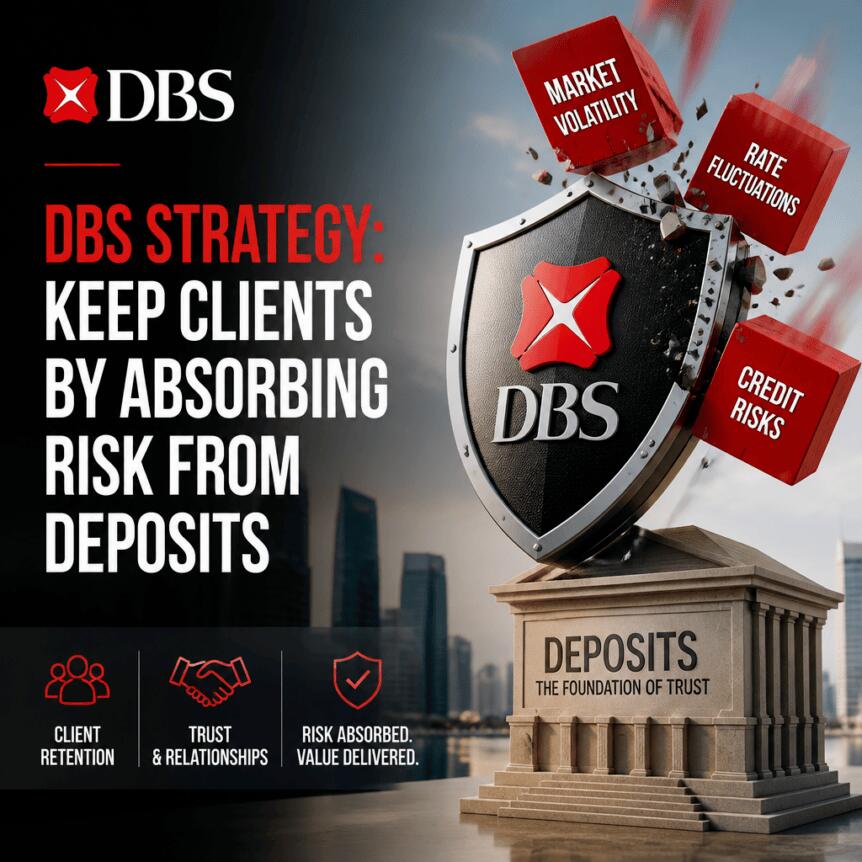
DBS has expanded its tokenization and stablecoin rails for corporate customers in Singapore by allowing eligible companies to source Circle’s USDC directly from the bank on Sundays—without routing orders through a public exchange. The move is aimed at reducing operational friction for treasury teams that need to settle invoices quickly, even outside traditional banking hours.
DBS also points to another weekend-ready option: moving dollars between client accounts in Singapore using its tokenized deposit link with JPMorgan. Taken together, the two capabilities show how banks are beginning to blend stablecoin payments and tokenized deposits into mainstream treasury workflows, rather than treating crypto assets as purely experimental side projects.
Key takeaways
DBS now enables eligible companies to obtain USDC directly from the bank, including on Sundays, via a Circle stablecoin distribution arrangement. The bank can also facilitate dollar transfers between Singapore accounts over a tokenized deposit link with JPMorgan, supporting weekend settlement needs. Once a company holds USDC, its treasurer can pay the next invoice without involving DBS for each payment step. DBS reported record fee revenue in its transaction services business, which helps frame what the bank may gain from these tokenized rails. Singapore’s MAS is advancing the broader tokenization ecosystem through central bank digital currency-linked bill experiments, with plans to expand trials in 2027.USDC access built for treasury timelines
The practical appeal of the DBS change is straightforward: some corporate treasury tasks don’t wait for Monday. Previously, a company that wanted USDC on a Sunday would typically have to convert through an exchange or counterpart operating at that time. With DBS now able to provide USDC directly to eligible firms, companies can line up stablecoin balances ahead of payment deadlines without relying on exchange availability or liquidity.
The article describes this as an additional conversion option for DBS clients. For treasurers, that matters because invoice payment timing is often constrained by internal approval processes as much as by market hours. If the stablecoin is already in hand, subsequent payments can be executed without re-engaging the bank for every invoice.
Weekend dollars, and a new role for tokenized deposits
Beyond stablecoin distribution, DBS also highlights the ability to move dollars between a company’s Singapore accounts during the weekend. The mechanism referenced is DBS’s tokenized deposit link with JPMorgan. While the details are framed at a high level, the point is that tokenized deposit infrastructure can support operational continuity when conventional settlement pathways are less convenient.
For corporate users, the workflow implied by the report looks like this: convert to USDC when needed (including on Sunday), then pay invoices using USDC without further involvement from DBS each time. That sequence can lower the number of conversions a company must perform and potentially reduce the time treasury staff spend coordinating settlement steps.
MAS bill collateral trials point to a broader tokenization push
DBS’s corporate stablecoin and tokenized deposit capabilities sit within a wider Singapore policy push. The Monetary Authority of Singapore (MAS) issued 100 million Singapore dollars (about $77.6 million) of four-week bills on Nov. 6. According to the provided information, the dealers paid in wholesale Singapore dollar central bank digital currency, and DBS participated as a securities dealer.
MAS plans to expand trials in 2027 to explore how institutions could use the bills as collateral. For investors and market participants, collateral is a key bottleneck in financial operations: the more smoothly eligible assets can be pledged and managed, the easier it is to build and scale new payment and settlement architectures. Even though the near-term bills experiment is still a trial, it signals that regulators are looking beyond one-off tests toward reusable collateral frameworks.
DBS earnings backdrop and what the bank has to defend
DBS’s quarterly results provide context for why the bank would invest in tokenized settlement options. In its third-quarter update, DBS reported that transaction services generated a record 268 million Singapore dollars in fees—up 8% year over year—before the timeline of the Nov. 6 central bank bills payment event.
The relationship between that fee base and the new stablecoin distribution is not quantified in the excerpt, but it matters for how readers should interpret the announcement. Tokenized rails can be positioned as efficiency improvements for customers; they can also become a source of fee revenue as corporate activity shifts from manual processes to structured conversion and settlement flows.
In the same vein, the article notes that for shareholders, the payoff will depend on several variables: how frequently treasury teams return to use the services, what DBS earns when funds move, and how much operating cash companies keep deposited. Those factors point to a broader reality in treasury products—recurring usage and balance behavior often determine whether innovation translates into sustainable economics.
What to watch next for corporates and regulators
For corporate users, the immediate question is practical: whether the “direct USDC from DBS” pathway becomes widely available to more eligible clients and how smoothly it integrates into existing treasury procedures. For the ecosystem as a whole, MAS’s planned expansion of collateral trials in 2027 is likely the next major milestone—one that could further connect stablecoin settlement, tokenized deposits, and regulated market infrastructure.
This article was originally published as DBS Strategy: Keep Clients by Absorbing Risk From Deposits on Crypto Breaking News – your trusted source for crypto news, Bitcoin news, and blockchain updates.
 Bengali (Bangladesh) ·
 English (United States) ·