 39 minutes ago
5

Bitcoin options traders have a new focal point: the $60,000 put strike, where approximately $900 million in outstanding notional positions has overtaken the once-dominant $100,000 call.
The change, reported by CoinDesk on November 16 using Deribit data, captures a market paying closer attention to downside protection after Bitcoin’s recent slide. The $100,000 call stood at about $867 million in open interest in the same snapshot.
Yet the headline needs care. A large outstanding put position is neither $900 million freshly spent on a crash bet nor a forecast that Bitcoin must fall below $60,000. Understanding the difference is central to reading the signal.
Bitcoin options: the protection trade moves into view
Nicolas Quatravaux, Paradigm’s head of EMEA, told CoinDesk: “OI is a stock, not a flow.” He attributed the change in ranking partly to traders closing bullish $100,000 calls, rather than a uniform rush into downside contracts.
That explanation changes the story. A defensive position can move to the top because another position shrinks. The ranking alone cannot show how much fresh fear entered the market that day, or how many investors changed their outlook.
The figures are a dated snapshot of outstanding exposure. They should not be read as a live order book, a single trader’s position or a scheduled sale of the underlying cryptocurrency.
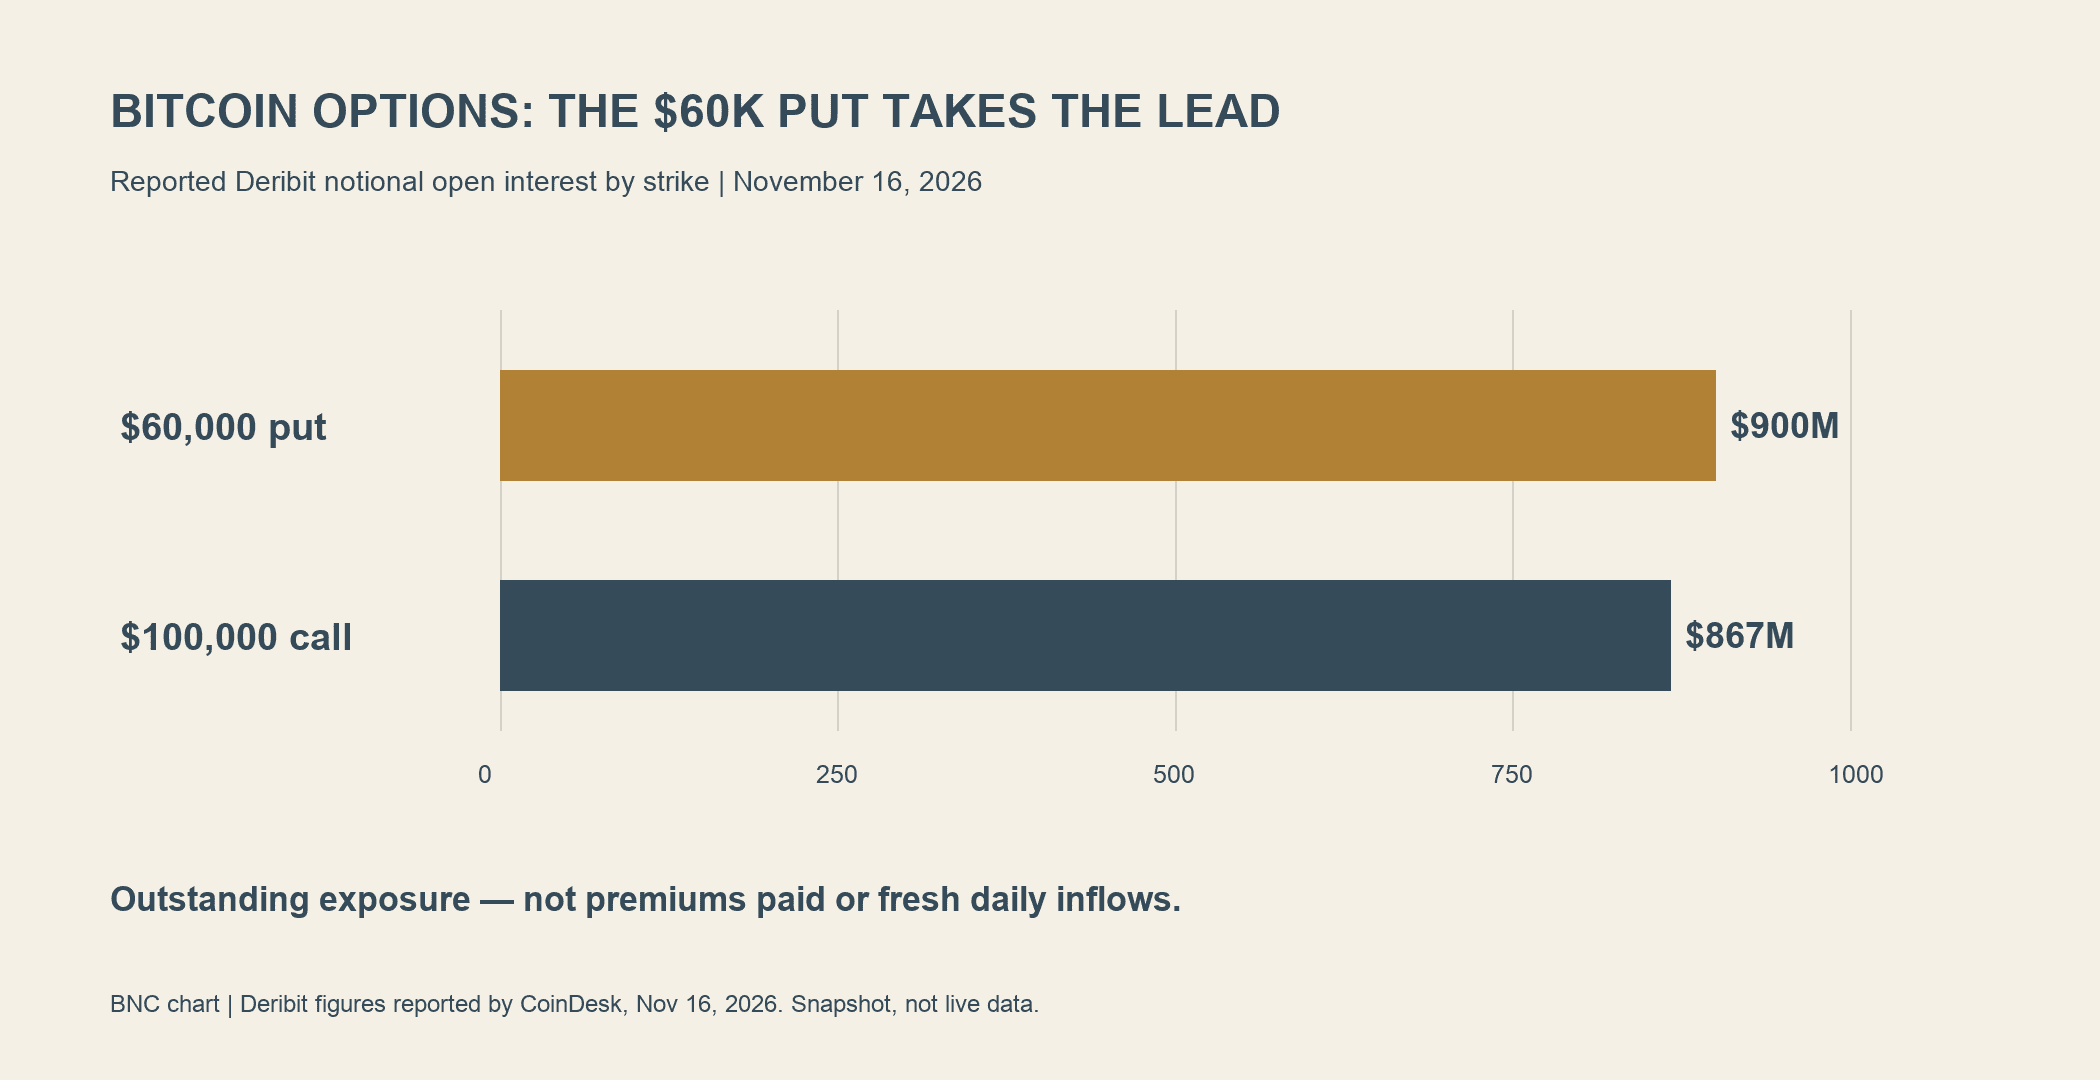 BNC chart from Deribit figures reported by CoinDesk on November 16. Outstanding notional exposure by strike, not premiums paid or new daily inflows.
Open interest counts contracts, not convictions
The Options Industry Council’s explanation of open interest separates outstanding contracts from session trading volume. When both counterparties open positions, open interest increases; when both close, it falls. A position changing hands can leave the count unchanged.
Consider a hypothetical transfer of ten contracts from an existing holder to a new buyer, with the other side staying open. Trading activity has occurred, but the market has not necessarily added ten new outstanding contracts. Confusing those measurements can exaggerate a shift in sentiment.
Every contract also has two sides. The buyer may want protection, while the seller may be collecting a premium or offsetting another exposure. The public total does not disclose either participant’s complete portfolio.
For a Bitcoin holder, buying protection can be consistent with keeping the coins. For an investor with several option legs, a put may be only one component of a strategy. Counting it as an isolated bearish vote loses that context.
A $60,000 strike is not a price target
Deribit’s contract specifications explain that its inverse BTC options represent one Bitcoin per contract. A put provides exposure to selling at its strike, with the eventual result determined under the exchange’s settlement rules.
The contract’s notional size describes the underlying exposure. Its premium is the separate price paid for the option. Treating the two as interchangeable can turn a large market exposure into a misleading claim about cash committed.
The strike also differs from the buyer’s break-even point. In a simplified dollar-denominated example, a $60,000 put bought for a $2,000 premium would require a settlement price below $58,000 to show a net expiry profit before fees. Those are illustrative numbers, not a quote for an available contract.
A settlement below $60,000 would give that hypothetical put intrinsic value, but would not automatically recover its purchase cost. For a hedger, however, limiting losses on a larger holding could matter more than the option’s standalone return.
Expiry dates can change the interpretation
Deribit’s guide to its metrics shows that open interest can be viewed across all expirations or filtered by a particular expiry. Its tools also separate outstanding positions from 24-hour put and call trading volumes.
That distinction matters because a near-term hedge and one extending months ahead answer different questions. Aggregating them at the same strike can reveal a popular protection level while obscuring when that protection is intended to apply.
A stronger assessment would compare matching expirations, changes in contract counts and prices paid for protection. Otherwise, a large but old position can overshadow a smaller, more informative new trade.
Changes in dollar notional also need a consistent valuation basis. If a dataset converts outstanding coin exposure using the prevailing Bitcoin price, the dollar amount can move even without an equivalent change in the number of contracts. Comparing like-for-like contract counts helps avoid that trap.
Compare derivatives with actual buying and selling
BNC’s report on two weeks of Bitcoin ETF withdrawals examined a separate measure: net money entering or leaving investment products. Options exposure and ETF flows can complement each other, but describe different activities.
An investor may retain fund shares while adding a hedge, or reduce spot exposure while closing an option. Without linked account data, those choices cannot be reconstructed from two aggregate headlines.
For readers watching the next move, the useful question is whether fresh defensive demand continues alongside weak spot buying. A reversal in either could change the picture. The $60,000 strike is a meaningful location to monitor; its prominence does not settle Bitcoin’s destination.
 Bengali (Bangladesh) ·
 English (United States) ·